 Analysis by Appwee
I judge a money app less by how many buttons it offers than by whether it helps during the awkward stretch between a bill and payday. That is the problem Dave: Credit, Cash & Money App is built around: giving people a way to seek a small cash cushion before their next paycheck, rather than relying immediately on an overdraft or a more formal borrowing option. In my view, that narrow purpose is the most useful lens for deciding whether it belongs on your phone.
Dave is a free finance app from Dave Operating LLC, available to people of all ages under its Everyone content rating. It has a 4.6 average from around 587,000 ratings, and has been installed over 10 million times. Those figures suggest that plenty of people are interested in this kind of short-term money tool, but they do not tell you whether it fits your own cash flow. I would treat it as a possible backup, not as a replacement for a dependable budget or a stable emergency fund.
What the cash cushion can—and cannot—do
The headline capability is access to an advance of up to $500. That ceiling is more meaningful than a tiny bridge for some urgent expenses, but it is still a limited amount, not a solution for a large bill or a prolonged income shortfall. The practical value is the timing: if a necessary expense arrives just before your pay, an advance may help you avoid a more expensive consequence such as an overdraft. It does not make the expense disappear; it moves money forward and leaves less room in a later pay period.
That distinction is easy to overlook when you are stressed. I would decide what the money is for before requesting it, then check what will be left after repayment and regular bills. If the answer is that next week’s essentials would become harder to cover, the advance may only shift the pinch. If it covers a short-lived timing gap and you have a realistic plan for the next deposit, it is more likely to serve as intended.
How I would use it in a real week
Picture a routine week in which a household bill and a necessary trip fall due before payday. I would first check the bank balance and upcoming payments, then compare the cost and timing of an advance with the likely cost of an overdraft or another available option. If I chose Dave, I would request only what addresses that specific gap rather than treating the maximum as a spending target. Once the paycheck arrived, I would revisit the budget and account for the amount that has to go back.
This is also where the app’s wider money tools can matter. The app’s current store version is 3.93.1, and its summary includes early pay, interest earnings, and finding work alongside cash access. Those are different ways of approaching a tight month: income timing, a place to earn interest, or an opportunity to bring in more money. I would look at them as separate tools rather than assume they all solve the same problem or are equally useful to every user.
A useful routine before tapping request
A small habit can make a short-term advance easier to evaluate: look at the next two pay periods, not just today’s balance. Note the bills that are already committed, any planned essentials, and the expected effect of repayment. This gives you a clearer answer to the important question—whether the advance fixes a temporary mismatch or creates another one later. I would also avoid using borrowed breathing room for discretionary purchases; that makes it harder to tell whether the app is genuinely helping.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
For someone whose income arrives on a predictable schedule, this kind of check can turn an emotional decision into a practical one. If income is irregular, the same check becomes even more important: a future deposit that is uncertain cannot safely be treated like cash already in hand. In that situation, I would compare Dave with options that do not require repayment from a particular upcoming paycheck, and I would be cautious about borrowing until the next income date is clearer.
Getting to Know Dave
Let’s start with the basics. The Dave app is designed to be your financial buddy, helping you avoid those pesky overdraft fees and providing you with a bit of a cushion when you need it most. It’s like having a financial safety net in your pocket, minus the judgment you might get from a traditional bank.
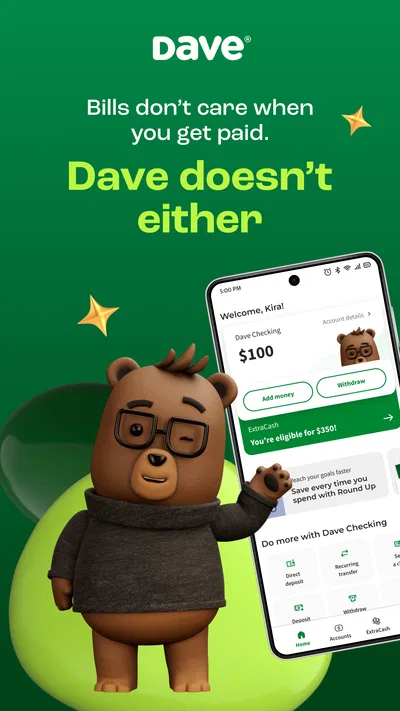
When I first downloaded the app, I was impressed by its clean and intuitive interface. It’s not overloaded with features, which is a good thing in my book. Everything you need is right there at your fingertips, making navigation a breeze. You don’t have to be a financial guru to figure this out – trust me, if I can do it, anyone can!
Key Features
So, what exactly does Dave offer? Here’s a breakdown of the standout features:
- Cash Advances: This is probably the app’s biggest selling point. You can request a cash advance of up to $100, which can be a lifesaver when you’re caught between paychecks. The best part? No interest or late fees!
- Budgeting Tool: Dave helps you keep track of your expenses by connecting to your bank account. It categorizes your spending and gives you a clear picture of where your money is going.
- Automatic Overdraft Alerts: Say goodbye to surprise overdraft fees. Dave sends you alerts when your account balance is running low, so you can avoid those dreaded charges.
- Side Hustle Suggestions: If you’re looking to boost your income, Dave provides suggestions for side gigs that fit your schedule and skills.
My Experience with Dave
Now, onto my personal experience. I signed up and linked my bank account in just a few minutes. The app’s setup process is straightforward, and I appreciated the transparency about what information was being accessed.
The cash advance feature works like a charm. I tested it out just to see how smooth the process was, and I was impressed by how quickly the funds were available. I also found the budgeting tool to be surprisingly insightful. It was eye-opening to see exactly how much I was spending on takeout each month (oops!).
One thing to note is that while the cash advance is interest-free, there is a $1 monthly membership fee. However, considering the potential savings from avoiding overdraft fees, it seems like a small price to pay for peace of mind.
Why You Might Love It
If you’re someone who occasionally needs a little extra cushion between paychecks, Dave could be a game-changer. It’s also a great tool for those looking to get a better handle on their spending habits without diving into complex budgeting software.
Plus, the side hustle suggestions are a nice touch. In today’s gig economy, having a few extra ways to earn money can be incredibly beneficial, and Dave makes it easy to explore those opportunities.
Who benefits most—and who should look elsewhere
I think Dave is most useful for someone with a short, specific cash-flow gap who wants a simple place to check possible options. It may also suit people who prefer seeing spending information and money tools in one app instead of juggling a separate budget tracker, bank app, and job-search tool. The convenience is appealing, but I would not confuse convenience with a guarantee that an advance is available or right for every situation.
If you routinely cannot cover essentials even after payday, a cash advance is unlikely to address the underlying problem. The same is true if your income is unpredictable and you cannot confidently plan around repayment. In those cases, speaking with a trusted financial counselor or contacting a bill provider about timing may be a better first step than borrowing again. I would also skip Dave if you want a full-featured financial planning system with detailed long-range forecasts; a dedicated budgeting tool may give you more control over categories, goals, and reports.
How it compares with familiar alternatives
Compared with a traditional bank overdraft, an advance can be attractive when avoiding an overdraft charge is the main goal, but it introduces its own repayment obligation and may not match every user’s timing needs. A credit card can offer a different kind of flexibility, yet it can also carry interest if a balance is not paid as expected. Dave is best considered alongside those choices, not as automatically cheaper or better in every case. Check the terms shown to you and compare the actual consequence of each option before deciding.
Compared with a standard budgeting app, Dave’s appeal is more immediate: it brings short-term cash access together with tools aimed at managing money and finding work. A dedicated budget app may be better if your priority is detailed planning rather than a bridge to payday. I would use Dave’s spending view to spot a pattern—such as repeated food or transport costs—and then make one small adjustment, rather than expecting a few categories alone to create a complete budget.
Details worth checking before relying on it
One practical question is whether a user can count on receiving the maximum advance. I would not plan a bill around the upper limit: treat the amount displayed for your own account as the relevant figure, and make a backup plan if the gap is larger. Another question is how quickly money will be usable. The experience described in the app may feel straightforward, but I would still leave a margin before a payment deadline instead of assuming every transfer or request will fit a last-minute timetable.
It is also worth separating “free to download” from the full cost of using a financial service. The app is free, but the published experience described here includes a monthly membership charge, so I would check the current terms in the app before signing up or continuing. The earlier description of a $1 fee should not be treated as a substitute for reviewing the terms that apply to you now. Likewise, “interest-free” does not mean that every other condition or possible cost can be ignored; read the request and repayment details before confirming.
For account access, I would take a minute to understand what information the app needs and why, then decide whether linking an account feels acceptable. That is a personal comfort question as much as a setup step. Keep your login details private, use the security options available on your device, and review linked services if you stop using the app. These are sensible habits for any finance app, especially one that works with a bank account.
Making the app a backup, not a routine
The strongest way to use an advance, in my opinion, is occasionally and deliberately. If the app helps you identify a coming shortfall early, you can compare options before a payment is due instead of reacting after an overdraft happens. The spending overview may also reveal whether the same kind of gap repeats every month. If it does, I would treat that as a signal to revisit bill dates, spending, or income—not as a reason to rely on another advance each cycle.
A useful test is to ask whether the next payday leaves you more stable or simply returns you to the same pressure point. If it is the latter, the convenience has not solved the problem. Dave may still help with a one-off mismatch, but recurring reliance is a reason to seek a more durable plan, even if that plan is as modest as setting aside a small amount when cash flow allows or contacting a provider before a bill becomes overdue.
Final Thoughts
All in all, the Dave: Credit, Cash & Money app is a solid choice for anyone looking to manage their finances a bit better and avoid those dreaded overdraft fees. It’s user-friendly, effective, and comes with a few perks that make it stand out from the crowd.
So, if you’re tired of stressing about your bank balance, give Dave a try. It might just become your new best financial friend. Until next time, happy app exploring!
Dave: Credit, Cash & Money App Pros and Cons
- Easy to navigate interface
- Quick access to cash advances
- No interest on cash advances
- Budgeting tools included
- Compatible with most banks
- Limited to U.S. users
- Requires a monthly fee
- Cash advance limits may be low
- No investment options
- Requires bank account linking
Dave: Credit, Cash & Money App Frequently Asked Questions
What is Dave: Credit, Cash & Money App?
Dave is a financial app designed to help users manage their money more effectively. It provides features like cash advances, budgeting tools, and credit-building options. The app aims to prevent overdraft fees and offer financial insights, making it a useful tool for personal finance management.
How does the cash advance feature work in Dave?
The cash advance feature in Dave allows users to borrow money against their next paycheck without incurring high-interest rates. Users can request advances up to $100, which can be received in their bank account within a few days. This service helps to cover unexpected expenses and avoid overdraft fees.
Is Dave a free app to use?
While downloading the Dave app is free, it operates on a membership model. Users pay a small monthly subscription fee to access its services. Additionally, there are no hidden fees for cash advances, although users are encouraged to leave a tip to support the service. The app also offers optional extra services that may incur additional costs.
How does Dave help with credit building?
Dave offers a credit-building tool that helps users improve their credit scores by reporting on-time payments to major credit bureaus. This feature is part of their broader financial management toolkit, designed to help users establish or rebuild credit, which can be crucial for securing loans or favorable interest rates in the future.
What security measures does Dave implement to protect users?
Dave employs robust security protocols to protect users' financial and personal information. The app uses bank-level encryption to secure data and offers two-factor authentication for enhanced account protection. These measures ensure that sensitive information remains confidential and secure from unauthorized access.
Gallery